Expanding beyond New York can create significant opportunities for startups, but it also introduces financial complexity that is easy to underestimate. A company may maintain its headquarters in Manhattan, employ engineers in Texas, serve customers in California, and establish a commercial presence in Massachusetts-all while operating through a single legal entity.
Although these activities may appear straightforward from an operational perspective, they can create distinct accounting, payroll, tax, and regulatory obligations.
For founders and finance leaders, the challenge is not simply managing additional transactions. It is building a financial infrastructure that supports growth across multiple states without compromising reporting accuracy, compliance, or cash flow visibility.
Why Multi-State Expansion Changes Financial Management
A company operating exclusively in New York typically manages a more concentrated set of financial obligations. As its geographic footprint expands, however, its financial responsibilities may become increasingly fragmented.
Each state establishes its own requirements for business taxation, employer registration, payroll withholding, sales tax, and certain reporting obligations. The applicable rules depend on factors such as the company’s activities, employee locations, revenue sources, and legal structure.
For example, hiring a remote employee in another state may create employer registration and withholding requirements. Generating revenue from customers in a new market may create additional tax considerations, even without a physical office.
The result is a growing need for coordinated financial oversight that extends beyond traditional bookkeeping.
1. Understand Where Your Company Has Financial and Tax Obligations
One of the first challenges in multi-state operations is determining where the company has established nexus-a sufficient connection with a state to trigger particular tax obligations.
Nexus can arise through physical activities, including employees, offices, or property. Depending on the state and tax involved, it may also arise through economic activity, such as sales exceeding a specified threshold.
New York, for example, applies an economic nexus threshold for certain corporate franchise tax purposes. For tax years beginning in 2024 through 2026, the applicable receipts threshold is $1.283 million, subject to special rules and other grounds for taxability.
Importantly, tax nexus and legal authorization to conduct business are separate questions. A company incorporated in Delaware may need authority to conduct business in New York, while its state tax obligations must be evaluated independently.
What founders should prioritize:
- Identify every state where employees, contractors, offices, property, or customers are located.
- Assess corporate income or franchise tax nexus separately from sales tax nexus.
- Determine whether foreign qualification or other state registrations are required.
- Maintain a state-by-state compliance calendar with clearly assigned responsibilities.
These assessments should be revisited as the company hires, enters new markets, or changes its operating model.
 2. Manage Payroll and Employment Compliance Across States
Distributed teams are now common among U.S. startups. However, employing people across multiple states can complicate payroll administration.
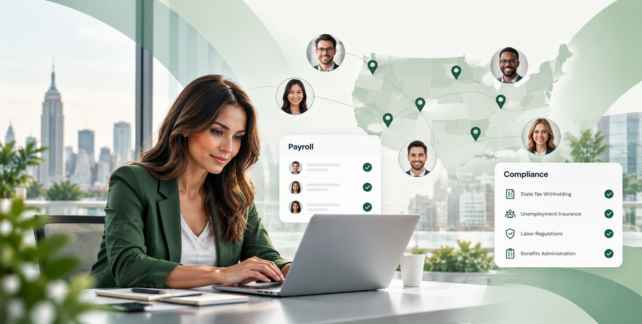
Companies may need to register for state income tax withholding, unemployment insurance, and other employer programs. Requirements can differ based on where employees physically perform their work, where the employer is located, and the applicable state rules.
New York presents additional considerations for employees working across state lines, including specific sourcing and withholding rules in certain circumstances.
A company should not assume that processing all employees through one payroll system automatically satisfies every state obligation.
Effective multi-state payroll management requires accurate employee work-location records, appropriate state registrations, and a process for reviewing relocations or changes in working arrangements.
Finance and HR teams should also coordinate on compensation policies, benefits, employment-related expenses, and payroll reconciliations to ensure that reported personnel costs remain accurate.
 3. Build a Consistent Accounting and Reporting Structure
As companies expand geographically, financial information often becomes fragmented across departments, systems, and business units.
This fragmentation makes it harder to answer fundamental management questions: Which markets generate the strongest margins? Where is spending accelerating? How does expansion affect operating cash flow?
A consistent chart of accounts provides the foundation for reliable reporting. Companies should establish standardized accounting classifications while using departments, locations, or other reporting dimensions to distinguish activities across states.
Where multiple legal entities exist, management must also address intercompany transactions, reconciliations, and consolidated financial reporting.
The objective is to maintain a single, consistent financial perspective while preserving the detail required for operational and tax reporting.
For growing startups, this becomes particularly important during fundraising, financial due diligence, and board reporting.
4. Allocate Revenue and Expenses Accurately
Multi-state financial management requires a clear distinction between internal management reporting and state tax reporting.
For management purposes, companies may allocate expenses across offices, departments, products, or markets to evaluate profitability and resource utilization.
State income tax apportionment, however, follows jurisdiction-specific statutory rules. Many states emphasize sales-based apportionment, but sourcing methods, tax bases, and exceptions vary.
A SaaS company, for example, may need to evaluate where receipts from software subscriptions or services are sourced under the applicable state’s rules. The location of its headquarters or billing department may not determine the result.
Companies should document their revenue sourcing methodology and retain supporting customer, contract, and transaction data.
Internal profitability allocations should be designed for decision-making, while tax apportionment calculations should be maintained under the applicable state requirements.
5. Maintain Cash Flow Visibility During Geographic Expansion
Expansion can increase operating expenses before additional revenue materializes.
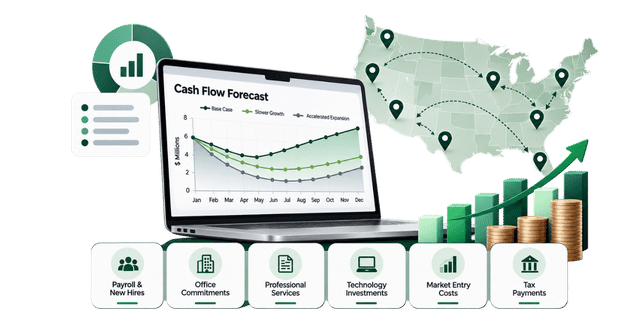
New hires, office commitments, professional services, technology investments, and market-entry costs may place pressure on liquidity. When these expenditures occur across several states, the financial impact can become difficult to monitor without centralized forecasting.
A rolling cash flow forecast helps leadership evaluate how expansion decisions affect runway and future funding requirements.
The forecast should incorporate expected collections, payroll, vendor commitments, capital expenditures, and estimated tax payments.
Scenario analysis is equally important. Management should understand the cash implications of slower customer acquisition, delayed hiring, higher compensation costs, or an accelerated expansion plan.
For venture-backed companies, this level of visibility supports more disciplined capital allocation and provides investors with a clearer picture of the company’s financial trajectory.
6. Establish Financial Controls That Scale With the Company
A multi-state operating model increases the number of financial processes requiring oversight.
Without consistent controls, companies may encounter duplicate vendor payments, inconsistent expense approvals, delayed reconciliations, or incomplete reporting.
A scalable control environment should include defined approval authority, documented accounting policies, regular account reconciliations, and clear ownership of tax and regulatory obligations.
Technology can automate transaction processing, expense management, and reporting workflows. However, automation should operate within an established framework of accountability and financial review.
As the company grows, finance leadership should periodically assess whether existing systems, personnel, and controls remain appropriate for the scale and complexity of operations.
7. Create a Practical Multi-State Finance Framework
Rather than addressing each new obligation independently, companies benefit from a structured expansion process.
| Priority | Recommended action |
|---|---|
| 1. Geographic footprint | Maintain an updated record of employee locations, business activities, and revenue by state. |
| 2. Registration and nexus | Review legal registrations and tax obligations before entering new markets. |
| 3. Payroll | Configure withholding, unemployment insurance, and applicable employer requirements. |
| 4. Accounting | Standardize the chart of accounts and geographic reporting dimensions. |
| 5. Tax reporting | Document revenue sourcing and state-specific filing responsibilities. |
| 6. Financial planning | Update cash flow forecasts and expansion scenarios regularly. |
| 7. Oversight | Assign clear responsibility for compliance, reporting, and internal controls. |
This framework should be incorporated into the company’s broader financial operating model rather than treated as a separate administrative exercise.
How ERB Proximo Supports Multi-State Financial Operations
Managing finance across New York and other U.S. states requires both strategic oversight and disciplined execution.
ERB Proximo supports growing companies through outsourced CFO leadership, financial planning and analysis, accounting, controllership, payroll coordination, tax coordination, and management reporting.
By connecting financial operations with forward-looking analysis, ERB Proximo helps founders maintain visibility into performance, anticipate financial requirements, and make informed decisions as their companies expand across the United States.
Frequently Asked Questions
1. Does a New York company need to register in every state where it has customers?
Not necessarily. Registration requirements depend on the company’s activities and each state’s laws. Having customers in a state does not automatically create a foreign qualification obligation, although revenue may create certain tax obligations.
2. Can hiring one remote employee create tax obligations in another state?
Yes. An employee working in another state can trigger employer registration, payroll withholding, unemployment insurance, and potentially business tax nexus obligations. The outcome depends on the state and the employee’s activities.
3. How should startups track revenue earned across different states?
Companies should maintain reliable customer and transaction data, including information relevant to state-specific sourcing rules. Revenue attribution for internal reporting may differ from the methodology required for state tax purposes.
4. Does a Delaware-incorporated startup operating in New York need to file taxes in both states?
Potentially. Incorporation in Delaware and business operations in New York can create separate obligations. The required filings and tax liabilities depend on the entity’s legal structure, activities, and applicable state rules.
5. Is one accounting system sufficient for multi-state operations?
Often, yes. A centralized accounting platform can support multi-state reporting if it captures the necessary geographic, departmental, and transaction-level information. The system must also support reliable reconciliations and appropriate reporting controls.
6. When should a growing startup consider outsourced CFO support?
Outsourced CFO support becomes particularly valuable when expansion introduces complex cash flow forecasting, multi-state reporting, additional compliance requirements, or greater investor expectations. The appropriate timing depends on operational complexity rather than revenue alone.
Building a Financial Foundation for U.S. Growth
Managing finance across New York and other states is not simply a compliance exercise. It is an essential component of sustainable expansion.
Companies that establish consistent accounting processes, clear reporting structures, disciplined cash flow management, and proactive financial oversight are better positioned to scale without losing control of their operations.
For founders, the goal is to ensure that financial infrastructure evolves alongside the company-supporting strategic decisions, investor confidence, and long-term growth.